
By Hannah Kanik, Reporter, San Francisco Business Times
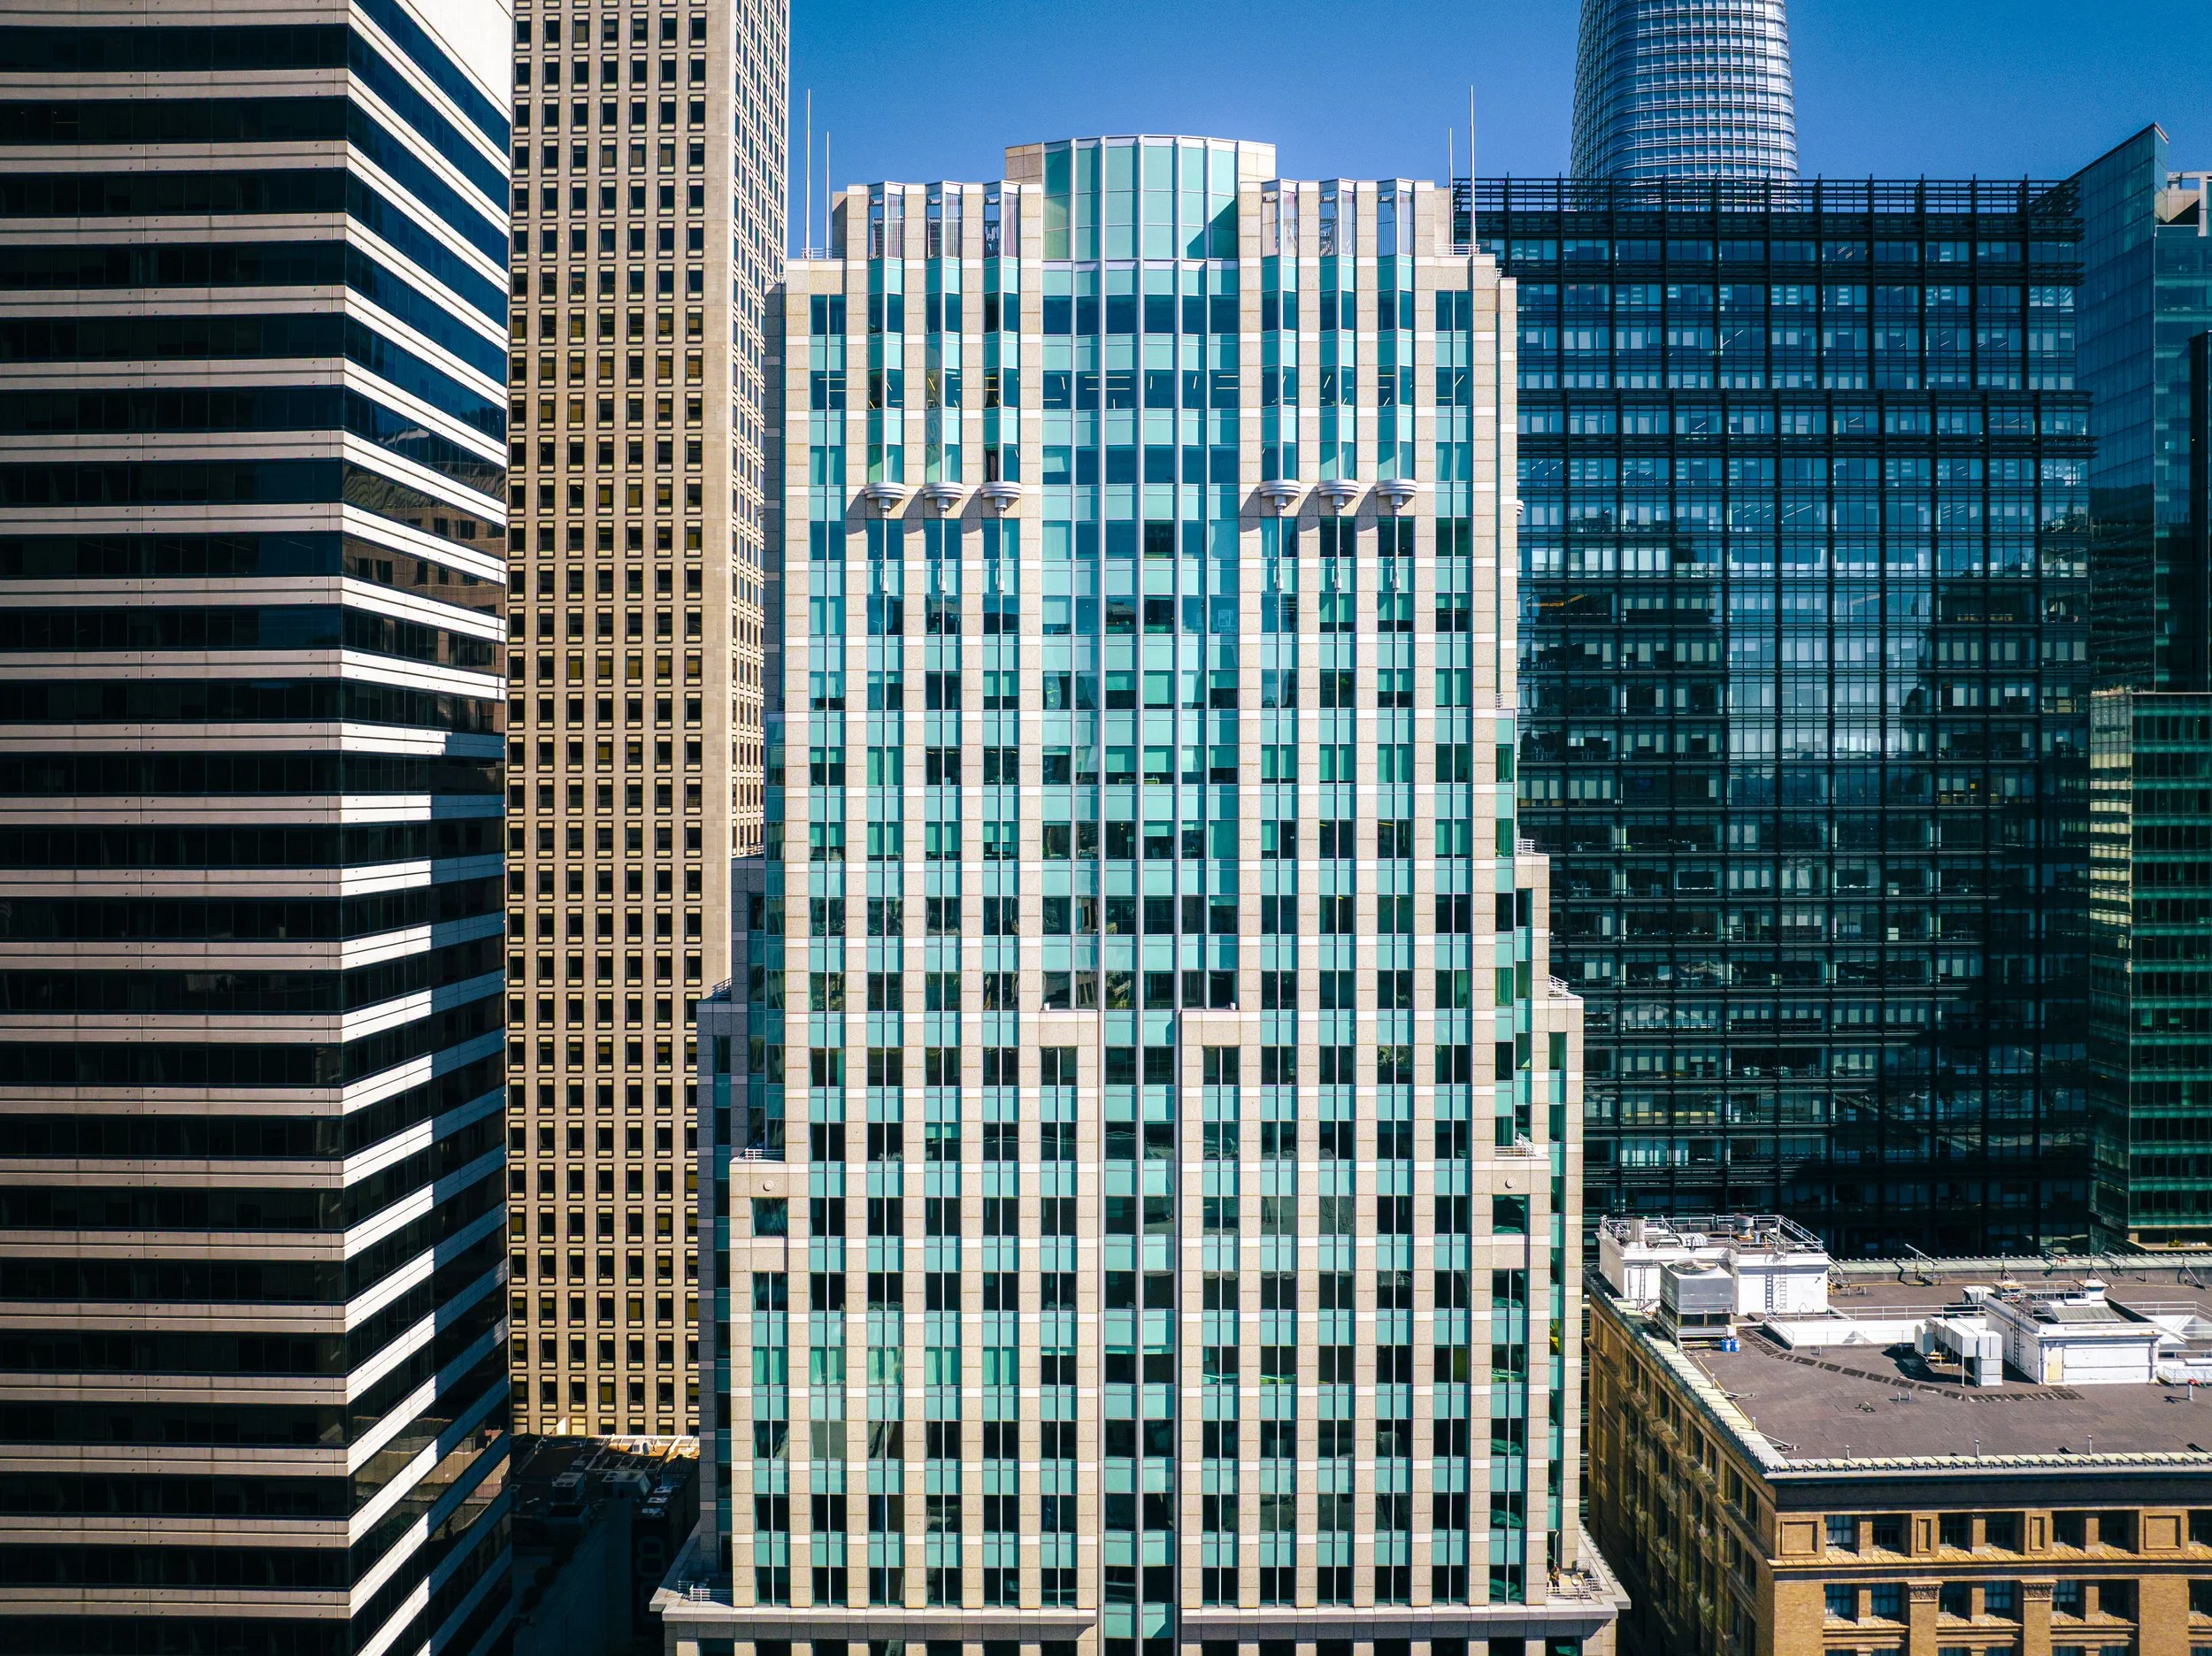
SAN FRANCISCO, CA – After losing its namesake tenant, the KPMG Building at 55 Second St. officially has a new owner, ending a period of uncertainty for one of San Francisco's best-known office buildings.
Real estate investor and developer Ellis Partners purchased the $187.5 million loan backed by the 386,193-square-foot building and subsequently acquired the property via a deed in lieu of foreclosure, records on file with the San Francisco Assessor-Recorder’s Office.
Ellis Partners confirmed the transaction to the Business Times, saying it had negotiated a deed-in-lieu agreement with the former owner and took ownership of the property in mid-October.
“Following KPMG’s recent move to its new San Francisco headquarters, the building is now 20 percent leased, providing significant leasing opportunities for tenants of all sizes along one of downtown’s most popular corridors,” an Ellis Partners spokesperson said, adding that "more details" would be coming.
Lender Canada Life Assurance Co. originated the $187.5 million loan backed by the building for Elecor Properties, then known as Paramount Group, in 2019. It listed the debt for sale in 2025, with pricing guidance at the equivalent of the mid- to high $300s per square foot range, roughly $130 to $145 million, a source told the Business Times last year.
Details on how much Ellis Partners spent to acquire the debt secured by the property were not clear. Given the building’s occupancy level and size, and the current capital markets activity in San Francisco, it’s likely the transaction landed in that range.
The sale comes roughly a year after Elecor wrote off its investment in the 25-story 55 2nd St., signaling to investors that the building’s worth had fallen below the value of the $187.5 million loan.
Some fully stabilized, Class A buildings have started trading for upwards of $600 per square foot. Distressed or low-occupancy office buildings have also seen values rise from the bottom of the market prices seen during the pandemic years, when buildings traded near $200 to $300 per square foot, though still significantly below their prepandemic values.
Moving on out
The debt backed by 55 Second was scheduled to mature in October, a month after the building’s longtime anchor tenant KPMG was scheduled to leave a 140,000-square-foot regional headquarters it called home for more than two decades. The consulting firm signed a new lease at 505 Howard for 96,000 square feet in a slight downsizing from its prior office.
Software company Rippling also left its 30,000 square foot office there to establish a new homebase at 430 California St; and Intercom, Inc. exited its 40,000-square-foot office at 55 Second for a new office at 85 Second St. That pushed the building’s vacancy down to 20%, which made it challenging for Elecor to refinance the maturing debt.
Elecor had owned the property with an unidentified joint-venture partner, acquiring a 44.1% stake in the building in July 2019 in a deal that valued the property at $402 million, roughly $1,057 per square foot. It was one of three significant acquisitions the firm made in the lead-up to the pandemic, alongside its purchases of 111 Sutter and One Market.
A spokesperson for Elecor said in a statement to the Business Times that it had been evaluating strategic alternatives for the 55 2nd St. property for some time, and is focused on its core portfolio of Class A office assets in New York City and San Francisco.
“Looking ahead, Elecor remains focused on advancing major investment initiatives at One Market Plaza and One Front Street, while continuing to enhance the tenant experience, strengthen the properties’ competitive positioning, and drive long-term value creation within the San Francisco office market,” the spokesperson said.
The investor launched a multimillion-dollar renovation project at both One Market and One Front Street, as well as two office buildings it owns in New York, to upgrade lobbies and add amenities like conference centers, bars, restaurants and other features in an effort to drive leasing activity.
Ellis Partners is a San Francisco-based real estate investment and development firm. It led the redevelopment of 1100 Broadway in Oakland — a major reimagination of the corner of 12th and Broadway into a modern office tower, and an adaptive reuse project Emery Tech, which transformed a World War II valve-manufacturing facility into Class A office space.